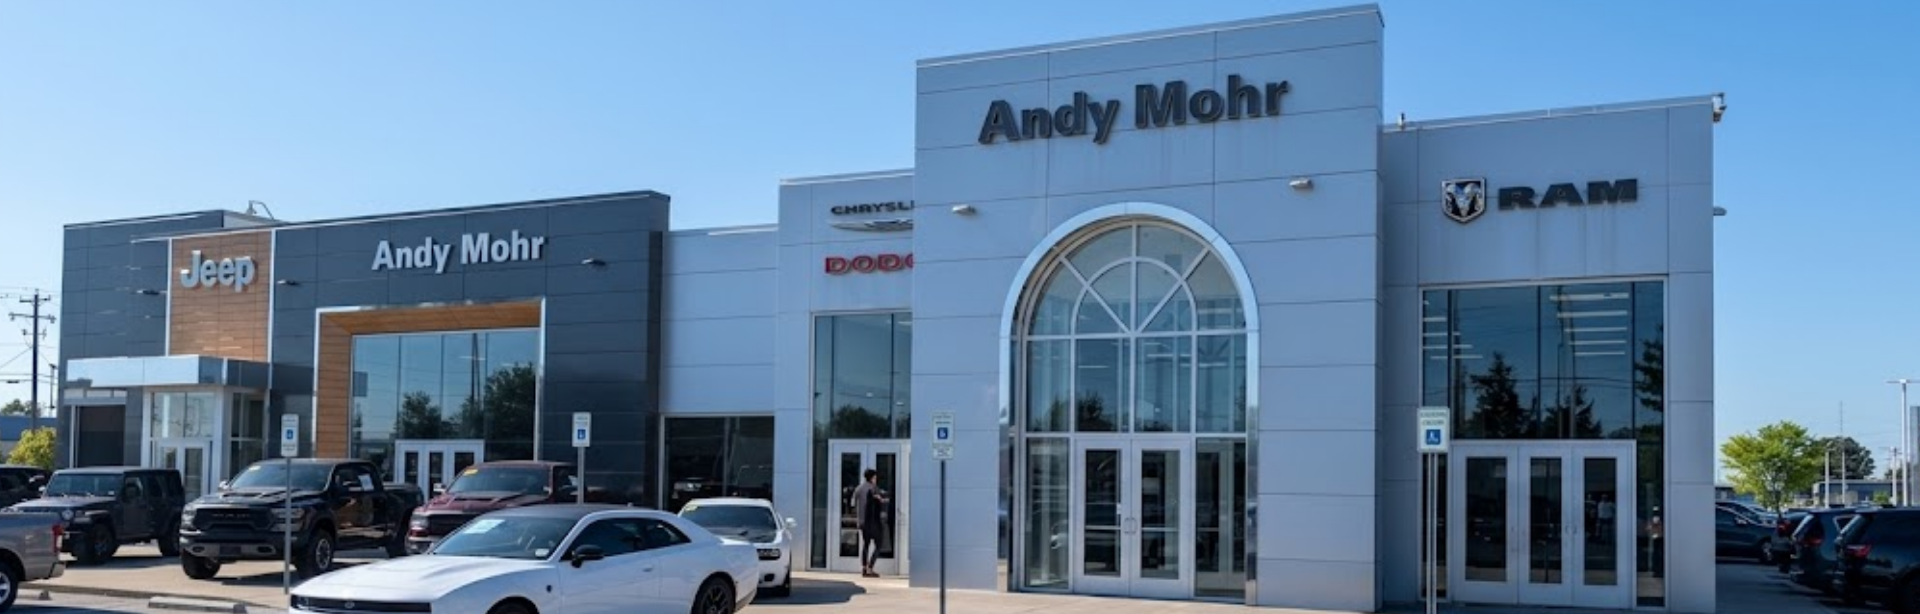
Deciding to finance or lease your next Chrysler, Dodge, Jeep, or RAM matters just as much as picking the right model for your daily 25-minute commute on I-465. Your decision often hinges on whether you want a permanent vehicle to conquer unpredictable Indianapolis winters or a shorter-term ride. Andy Mohr Chrysler Dodge Jeep Ram serves as a reliable, long-standing automotive partner for drivers in Indianapolis and nearby Zionsville, Carmel, Brownsburg, and Fishers. Backed by trusted experience and deep local knowledge, we specialize in expertly servicing and maintaining your Chrysler, Dodge, Jeep, and RAM vehicles long after you sign the paperwork. Let's break down your payment options so you can hit the road with undeniable confidence.
Key Takeaways (TL; DR)
Securing the keys to a bold new Dodge Charger or a highly capable Jeep Grand Cherokee comes down to understanding your financing options up front. For drivers across Indianapolis and nearby Carmel, knowing exactly how credit scores, lease terms, and lender programs work means you can hit I-465 with a payment plan that actually fits your budget.
- Your Credit Profile Sets the Pace: Your FICO score directly dictates the interest rates you qualify for when financing a rugged Ram 1500 or a versatile Chrysler Pacifica minivan. Securing a higher score means lower rates, keeping your monthly payments manageable and saving you serious cash over a typical 60- or 72-month loan term.
- Direct Lender Perks: Utilizing manufacturer-backed lenders like Chrysler Capital unlocks competitive rates and exclusive bonus cash incentives you won't always find at a standard credit union. You can even lock in your pre-approval online from your couch in Zionsville, cutting out the waiting game at the dealership.
- Leasing vs. Financing: Traditional financing builds equity over time until you own the vehicle outright. On the flip side, leasing acts as a short-term commitment with lower monthly payments, though you will need to stick to annual mileage caps-typically 10,000 to 15,000 miles-which works flawlessly if you just commute down Meridian Street.
- Lease-End Flexibility: When your two- or three-year term wraps up, you hold all the cards. You can hand the keys back, trade up to the newest Jeep Wrangler, or simply buy out your current ride for its predetermined residual value if it has been your go-to rig for hauling gear to Eagle Creek Park.
- Targeted Rebates and Incentives: Automakers frequently roll out targeted bonus cash programs to aggressively lower your bottom line. Active military members, recent college graduates, and returning lessees can routinely tap into extra savings-often $500 or more-to instantly drop their drive-off costs.
- Preparation is Power: Walking in prepared puts you in the driver's seat. Pull your credit report beforehand, nail down a firm budget using the classic 20% down payment rule, and bring your recent pay stubs so you can bypass the red tape and get straight to the test drive.
Taking Command: How Automotive Financing Works
Financing a vehicle simply means partnering with a lender-such as Stellantis Financial Services (SFS) or a local bank-to cover the upfront purchase price. You then pay back that principal amount, alongside interest, in set monthly installments over a specific period known as your loan term, which typically ranges from 36 to 72 months. What this means for Indianapolis drivers is predictable budgeting that puts you behind the wheel today. Whether you are financing a rugged gas-powered Jeep Wrangler for weekend kayaking trips at Eagle Creek Park or commanding a spacious Dodge Durango SUV to haul your family's gear around I-465, an auto loan maps out a clear path to total ownership.
With every payment you make, you build equity, which is the actual cash value of the vehicle that you own outright. Once that final check clears, the lender signs over the title, and the machine is completely yours. This route is perfect for Hoosiers who refuse to be held back by mileage limits-you can tackle a daily commute down Mass Ave or take a cross-country road trip without stressing over odometer penalties. Plus, financing gives you the absolute freedom to customize your Chrysler, Dodge, Jeep, or RAM exactly how you see fit.
How Stellantis Financial Services Empowers Your Drive

Stellantis Financial Services (SFS) is the official financing powerhouse for Chrysler, Dodge, Jeep, and RAM, directly connecting buyers with factory-backed auto loans and flexible lease structures. Whether you want to lock in competitive Annual Percentage Rates (APRs) based on your credit tier or set up a 36-month lease on a bold, gas-powered 2027 Dodge Durango, SFS handles the heavy lifting behind the scenes. For drivers around Indianapolis, this streamlined approach matters because it fast-tracks your approval and unlocks exclusive manufacturer incentives-keeping your payments in check so you can confidently cruise down I-465 or hit the tailgate at the Indianapolis Motor Speedway.
Securing your next ride starts before you even step on the lot, thanks to straightforward online pre-approval. Submitting your details ahead of time lets SFS review your credit history and income to determine your exact eligibility. Keep in mind that loan terms and lease offers vary by credit, meaning a higher score typically opens the door to aggressive loyalty bonuses or promotional APRs. Think about the math: shaving just a fraction of a point off your interest rate through an exclusive Stellantis Financial Services incentive can drastically reduce your total payout compared to a standard bank loan, freeing up cash for shopping runs to Castleton Square Mall or weekend road trips from Brownsburg.
When you are ready to command a gas-powered Dodge Charger 4-Door down Mass Ave or put a rugged RAM 1500 to work, SFS integrates seamlessly right at the dealership level. They evaluate your unique financial footprint to build a customized payment plan that fuels your automotive passion without compromising your daily budget. Ultimately, it delivers unapologetic American performance backed by straightforward, muscular financing.
What It Means to Lease a Chrysler, Dodge, Jeep, or Ram
Leasing a vehicle like a Jeep Grand Cherokee or a Dodge Charger 4-Door operates much like a long-term usage agreement, focusing on your time behind the wheel rather than absolute ownership. Instead of absorbing the entire sticker price, you commit to a specific timeframe-most commonly a 24- or 36-month term. Over that period, your primary expense is depreciation. This is calculated by taking the vehicle's initial price and subtracting its estimated future worth at the end of the contract, an industry metric known as the residual value. You also cover applicable taxes, standard dealership fees, and a money factor, which functions exactly like the interest rate on a traditional auto loan.
What this means for Indianapolis drivers is the ability to lock in a highly predictable transportation budget. Say your normal routine involves daily commuting loops on I-465 or hauling the family to weekend events at Eagle Creek Park. By matching those driving habits to a standard 10,000- or 12,000-mile annual lease limit, you only pay for the exact utility you extract from the vehicle. Because your payments strictly cover that temporary depreciation window rather than the full MSRP, the monthly outlay is typically lower than financing a purchase. It is a straightforward financial structure that simply cycles you out of the car right before long-term, out-of-pocket maintenance usually begins.
Command Your Next Move: End-of-Lease Options for Your Chrysler, Dodge, Jeep, or RAM
When your lease term approaches the finish line, you hold the power to dictate what happens next. Whether you want to unleash a brand-new model on I-465 or keep the exact machine you've relied on for daily drives into Zionsville, you have three distinct avenues. Taking decisive action early guarantees you stay in control of your commute without missing a beat.
- Purchase Your Current Lease: If you refuse to give up the keys, buy it. Your original contract locks in a guaranteed residual purchase price. For example, if you kept your mileage low while commuting down Meridian Street, your vehicle's current market value might actually sit higher than that residual number-giving you instant equity the moment you buy it out.
- Upgrade to a New Vehicle: Ready for a fresh rush of adrenaline or the latest Uconnect® technology? Turn in your current vehicle and start a new lease or finance contract. This is the fastest way to grab a newly redesigned Dodge Charger or a spacious Jeep Grand Cherokee right off the showroom floor.
- Walk Away Clean: You can always choose to return the vehicle and move on. Just remember to schedule a standard pre-return inspection roughly 60 to 90 days before the contract ends to flag any excess mileage or wear from rough Indiana winters. Before handing it back, running a quick check on the Kelley Blue Book homepage can help verify you aren't leaving money on the table.
Financing vs. Leasing: Which Path Fits Your Drive?

Financing builds equity until you own the vehicle outright, while leasing covers depreciation over a typical 36-month term with a 10,000-mile annual cap. For Indianapolis drivers, this dictates your strategy: if you log heavy miles commuting on I-465, financing a Dodge Charger avoids overage penalties, but if you just cruise around Broad Ripple, leasing lowers your monthly payment.
| Feature | Financing a Chrysler, Dodge, Jeep, or RAM | Leasing a Chrysler, Dodge, Jeep, or RAM |
|---|---|---|
| Ownership | Title transfers to you once the loan is fully paid off. | The dealership or financial institution retains ownership. |
| Monthly Payments | Generally higher, because payments cover the entire purchase price. | Usually lower, since you are only paying for the expected depreciation. |
| Upfront Costs | A cash down payment or trade-in is highly recommended to offset the total loan. | Typically requires the first month's payment alongside standard acquisition fees. |
| Customization | Total freedom to install performance parts, lift kits, or custom modifications. | The vehicle must be returned in its original factory condition. |
| Mileage | Drive as far as you want with zero mileage restrictions. | Strict annual limits apply (often 10,000 miles); exceeding them triggers per-mile penalties. |
| Wear & Tear | Dents and scratches simply lower your own future resale value. | You will face out-of-pocket penalty fees for any excess damage upon return. |
| End of Term | Keep driving payment-free, sell the vehicle, or trade it in. | Turn the keys in, buy the vehicle out, or start a fresh lease on a new model. |
The Core Elements That Drive Your Financing and Lease Terms
What exactly dictates the rate and duration of your auto loan or lease? Essentially, lenders look at your financial footprint-namely your credit history and debt-to-income ratio-combined with the specific Chrysler, Dodge, Jeep, or RAM vehicle you intend to park in your driveway. Nailing down favorable terms matters for Indianapolis drivers because it dictates how comfortably you can cruise I-465 or make weekend trips to the Indianapolis Motor Speedway without stretching your monthly budget. Consider this quick contrast: putting 20% down instead of 10% on a spacious Dodge Durango SUV with a standard 60-month loan doesn't just lower your monthly bill; it slashes the total interest you pay over the life of the agreement.
- Credit Score: Your track record with borrowed money is the heaviest hitter. A robust score commands the most aggressive, lowest interest rates.
- Down Payment: Bringing more cash to the table directly reduces your starting principal balance. That means less total interest accumulating while you own the vehicle.
- Term Length: Stretching a loan out to 72 months drops the immediate monthly cost for easier budgeting, whereas a shorter 48-month term builds equity faster and minimizes long-term interest.
- Vehicle Price and Type: Whether you are securing a family-hauling Chrysler Pacifica minivan or a powerful, electric Dodge Charger Daytona, the final price tag sets the baseline. Furthermore, brand-new models frequently qualify for specialized manufacturer promotional rates.
- Debt-to-Income (DTI) Ratio: Lenders compare your gross monthly income against existing debts to ensure a new car payment will not redline your household finances.
- Trade-In Value: Swapping out your current ride acts just like cash. If you are upgrading your daily driver for the Carmel commute, any positive equity directly shrinks the amount you need to finance.
What Special Chrysler, Dodge, Jeep, and RAM Programs Can You Unleash?
Chrysler, Dodge, Jeep, and RAM provide aggressive financing and lease programs designed to put you behind the wheel of a high-performance machine without draining your wallet. For Indianapolis drivers, maximizing these incentives means more financial freedom to upgrade to serious towing capability or track-ready power. Whether you are commuting the loop on I-465 or heading to a weekend race at the Indianapolis Motor Speedway, snagging the right rebate directly reduces your overall cost. You can often track national incentive rollouts on Dodge.com, but here is a look at the core programs built to reward you.
- College Graduate Program: Fresh out of school? Start your career with a ride that commands attention. Recent graduates who provide proof of their degree and current employment can score bonus cash toward their purchase or lease. A simple rebate like this easily offsets a decent chunk of your initial signing fees compared to bringing straight cash to the table.
- Military Appreciation Offer: We respect the drive of those who serve. Eligible active, reserve, and retired U.S. military members-along with their spouses-frequently qualify for exclusive bonus cash. It is a straightforward way to knock down the final price of a heavy-duty workhorse like the RAM 2500 or a family-hauling Dodge Durango.
- Brand Loyalty and Conquest Benefits: Sticking with the family pays off. Current Chrysler, Dodge, Jeep, or RAM owners routinely get loyalty cash on select new models. On the flip side, "conquest" cash is sometimes offered to drivers trading in a competitor's vehicle-giving you a financial edge for stepping up to true American muscle.
- Regional Promotions: Factory offers shift depending on the time of year and local demand. If you need to tackle Indiana's messy winter snows, you might catch targeted lease deals on 4x4 Jeep models perfect for navigating a slick Meridian Street. Once summer hits, promotions often pivot to road-trip-ready haulers like the Chrysler Pacifica minivan.
Securing Your Chrysler, Dodge, Jeep, or RAM Financing

Instead of spending a beautiful weekend stuck at a desk, you can kickstart the approval process from your couch in the Broad Ripple neighborhood and claim the keys to a bold new Dodge Durango or Jeep Grand Cherokee. Streamlining your application means less time waiting on paperwork and more time dominating your daily commute on Interstate 465 or hauling the family to White River State Park. Here is how to confidently navigate the loan or lease process from start to finish.
- Get Pre-Qualified First: Find out where your buying power stands before you ever walk the lot. This initial step gives you a strong estimate of your potential loan terms without placing a hard inquiry on your credit history.
- Gather Your Essential Documents: Come ready to deal. To finalize the paperwork, you will need a valid state-issued driver's license, recent proof of income, documentation confirming your current residence, and up-to-date auto insurance coverage.
- Submit the Full Application: When you are officially ready to lock down that RAM 1500 or all-electric Dodge Charger Daytona, we process the formal paperwork. This involves a hard credit check to secure your exact Annual Percentage Rate (APR) from our lender network.
- Review the Terms and Sign: Take control of the final numbers. You will verify your exact monthly payment, the total term length, the confirmed APR, and any optional Mopar® Vehicle Protection plans before putting your signature on the dotted line.
Cash or Financing: Funding Your Next Machine
So, should you drop the full stack of bills or take out an auto loan? Handing over cash for a powerhouse like the 2027 Dodge Durango SUV delivers instant ownership and absolute freedom from monthly statements. What this means for Indianapolis drivers is true financial peace of mind-you hold the title the second you fire up the engine and merge onto I-465. Consider the basic math: paying upfront rather than financing over a standard 60-month term easily eliminates thousands of dollars in interest charges over the life of the vehicle. That said, draining a massive chunk of your liquid savings means those funds aren't available if life throws a curveball. You command the road immediately, but your bank account takes a sudden, heavy hit.
On the flip side, financing lets you keep your hard-earned cash safely in the bank while breaking the purchase price into manageable monthly chunks. Whether you crave the raw energy of a gas-powered Dodge Charger 2-Door or need the rugged capability of a Jeep Wrangler for weekend hauling to Eagle Creek Park, an auto loan preserves your flexibility. Financing terms generally range from 36 to 72 months, giving you the power to dial in a payment structure that fits your exact budget. You'll undeniably pay more in the long run because of the added interest, but you won't sacrifice your rainy-day fund to grab the keys. Ultimately, the smartest choice comes down to your current cash flow and how much you value having liquid assets ready to deploy.
What Are the Pros and Cons of Each Payment Method?
Choosing how to pay for your next Chrysler, Dodge, Jeep, or RAM depends entirely on your driving habits. Buying delivers long-term freedom and equity, while leasing puts you in a newer ride with less commitment. Let's break down both paths for Indianapolis drivers.
Pros of Financing
- Ultimate Ownership: Once you clear that final payment, the vehicle is 100% yours to keep, sell, or pass down to a family member.
- Zero Mileage Restrictions: Finance a bold Dodge Charger or a heavy-duty RAM 2500, and you can loop I-465 every day or take cross-country road trips without sweating overage penalties.
- Total Customization: Want to add a suspension lift to your Jeep Wrangler or bolt on performance exhaust parts? Buying means you have the absolute power to modify your ride exactly how you want it.
- Building Equity: Every monthly payment increases your stake in the vehicle, giving you tangible trade-in value later on.
Cons of Financing
- Higher Monthly Cost: Because you are paying for the entire purchase price of a premium SUV like the Jeep Grand Cherokee, your monthly payments will naturally run higher than if you leased the same model.
- Post-Warranty Repairs: Once your factory 3-year/36,000-mile Basic Limited Warranty and 5-year/60,000-mile Powertrain Limited Warranty expire, any mechanical repairs fall entirely on your shoulders.
- Market Depreciation: The resale value of any vehicle drops over time. When you own it, you take on the financial risk of market fluctuations when it is finally time to sell.
Pros of Leasing
- More Muscle for Less Money: Since you are only paying for the vehicle's depreciation during your term, your monthly payments are notably lower, freeing up your budget.
- Constant Upgrades: Turning in your keys every few years means you always have the latest safety technology and interior styling for weekend trips to Castleton Square Mall.
- Built-In Peace of Mind: Most lease contracts last three years, lining up perfectly with the standard 3-year/36,000-mile Basic Limited Warranty. For local drivers, that means fewer out-of-pocket costs for unexpected repairs.
- Hassle-Free Returns: You skip the trade-in negotiations completely. Just drop the vehicle off at the end of your contract and pick out a fresh one.
Cons of Leasing
- Strict Mileage Caps: If your daily commute from Brownsburg to downtown Indianapolis pushes you past your limit, you will face penalties. For instance, driving 15,000 miles a year on a 12,000-mile contract at a 25-cent overage fee changes your end-of-year cost by $750.
- No Equity Earned: You return the vehicle at the end of the term with nothing to show for your past payments, similar to renting an apartment.
- Wear and Tear Charges: Hauling muddy youth sports gear to Eagle Creek Park in a leased Chrysler Pacifica? Excessive interior stains or exterior scratches will result in extra fees at turn-in.
- Zero Modifications: The vehicle must be returned in its original factory condition, meaning no permanent aftermarket performance parts, aggressive styling changes, or off-road modifications.
How to Score the Ultimate Deal on Your Next Ride

To get the absolute best deal on your next vehicle, you need to lock down your finances, compare rates, and time your purchase perfectly before you ever set foot on the lot. Walking into the showroom with a solid game plan puts you firmly in the driver's seat. For Indianapolis drivers, knowing exactly how to leverage these numbers means keeping more cash in your pocket for weekend excursions to Eagle Creek Park or tailgating over at the Indianapolis Motor Speedway. By doing the heavy lifting before you fall in love with the rumble of a 2027 Dodge Durango SUV or the rugged utility of a Jeep Gladiator truck, you get to dictate the terms of the negotiation.
- Audit Your Credit Score Early: Don't let a surprise ding on your report slow your momentum. Pull your credit history weeks before you shop. Securing a prime score-typically 720 or higher-unlocks the lowest APRs and gives you maximum buying power.
- Shop Your Financing Rates: Compare auto loan quotes from your local bank or credit union alongside dealership offers. While promotional financing from the manufacturer often beats outside lenders, holding multiple approvals gives you serious leverage.
- Strike at the Right Time: Timing is everything in this business. Shopping late in the month, at the end of a quarter, or right as the next model year hits the lot-like when the 2027 RAM 1500 trucks arrive-often triggers aggressive incentives to move inventory.
- Lock Down the Price First: Treat the vehicle's bottom line as a completely separate conversation from your trade-in or financing. Whether you are eyeing the pulse-pounding Dodge Charger 2-Door sport model or a family-ready Chrysler Pacifica minivan, establish the total purchase price before discussing a 60-month or 72-month loan term.
- Master the Math: If you are financing, focus on the APR and the total amount financed rather than letting a low monthly payment distract you. For a lease, you need to understand the capitalized cost (the negotiated price of the vehicle), the residual value, and the money factor (the lease's interest rate).
- Do Your Trade-In Homework: Know exactly what your current ride is worth before cruising down Interstate 465 to make a deal. Use trusted industry resources like Kelley Blue Book or Edmunds to establish a rock-solid baseline value so you can negotiate with confidence.
Frequently Asked Questions (FAQs)
What amenities does Andy Mohr Chrysler Dodge Jeep Ram offer if I wait for my vehicle to be serviced?
Andy Mohr Chrysler Dodge Jeep Ram provides a children-friendly waiting area stocked with complimentary snacks and beverages so your family stays comfortable. Our team also offers convenient service perks like complimentary car washes and loaner vehicles to get you right back on I-465 without skipping a beat.
How does Andy Mohr Chrysler Dodge Jeep Ram support the local community?
Since 2003, Andy Mohr Chrysler Dodge Jeep Ram has proudly backed local initiatives, including dedicated support for the American Cancer Society and Toys for Tots. We believe in actively giving back to the hard-working community that drives with us everywhere from Mass Ave festivals to their daily morning commutes.
What credit score do I need for Chrysler, Dodge, Jeep, and RAM financing?
While our finance team successfully works with a wide range of credit profiles, higher scores typically unlock the most aggressive promotional offers and top-tier rates. Whether you are commuting 25 minutes down I-70 or running errands near Castleton Square Mall, demonstrating strong income and bringing a solid down payment gives you the power to secure optimal terms.
Is it hard to get approved by Chrysler, Dodge, Jeep, and RAM's captive lender?
Securing approval depends on your unique financial footprint, but our dedicated finance experts actively work alongside you to construct a powerful solution. Showing steady income and a clean history makes it much easier to dominate your daily drive in a capable vehicle built to conquer Indiana's four distinct seasons.
Does Chrysler, Dodge, Jeep, and RAM ever offer 0% financing?
Yes, you can occasionally capture thrilling 0% financing rates on select new models during major regional or national sales events. Our financing team tracks down these bold promotions for well-qualified buyers, ensuring you can take command of the open road for less.
Can I negotiate the price on a lease?
Absolutely, the vehicle's capitalized cost is negotiable, and our staff will sit down directly with you to forge a fair agreement. We work hard to ensure your monthly payment comfortably fits your lifestyle, leaving you plenty of budget to haul the family's sports gear to Eagle Creek Park.